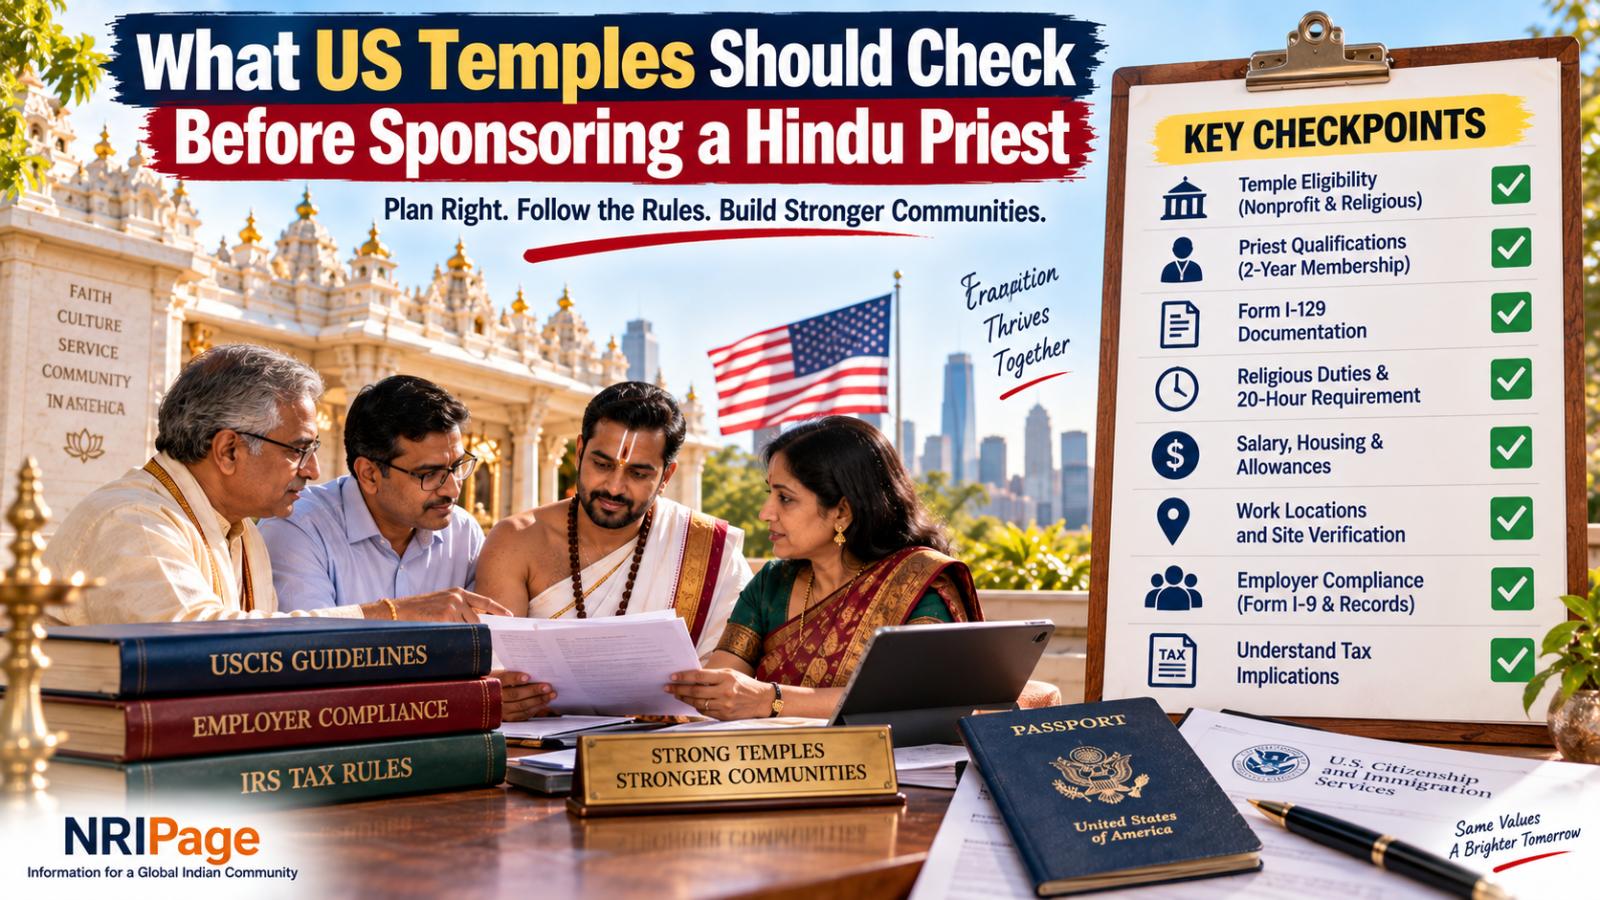
US temples sponsoring Hindu priests under R-1 rules should verify their own nonprofit eligibility, the priest's denominational membership and qualifications, religious duties, work hours, compensation and work location before filing Form I-129.
US temples planning to sponsor a Hindu priest should review both the temple's eligibility and the priest's qualifications before filing an R-1 petition. The process requires documentation about the religious organization, position, compensation and intended employment.
Confirm the temple qualifies to sponsor
An R-1 petitioner must generally be a bona fide nonprofit religious organization in the United States, an organization covered by a qualifying religious group exemption, or an eligible nonprofit affiliated with a religious denomination.
USCIS Form I-129 instructions require supporting evidence such as a current IRS tax-exemption determination letter and, where applicable, documents proving the organization's religious nature and denominational affiliation.
Verify the priest and position
Before sponsoring a priest, the temple should confirm that the worker has belonged to the qualifying religious denomination for at least two years immediately before the petition is filed.
The position must be as a minister or in a qualifying religious vocation or occupation, and R-1 employment must average at least 20 hours per week.
The petition should accurately describe the priest's daily religious duties rather than relying only on a job title.
Document salary, housing and work locations
USCIS requires verifiable evidence explaining how the temple intends to compensate the religious worker, whether through salary or non-salaried support.
If the arrangement includes housing, meals or other benefits, the temple should document them clearly. Work locations should also match the petition because USCIS may verify information about the organization and employment location through compliance inspections. USCIS policy permits religious-worker site inspections before or after petition approval.
Complete employment and tax compliance
After hiring, temples must also follow ordinary employer requirements. US employers generally must complete Form I-9 to verify each new employee's identity and authorization to work.
Tax treatment can be specialized for clergy. The IRS says ministers may be employees under common-law rules, while compensation, ceremony fees and qualifying housing allowances can receive different tax treatment.
For temples, consistent documentation is critical: the actual duties, hours, compensation and work locations should match the arrangement presented to USCIS. Changes to the priest's employment should be reviewed before the temple assumes the original approval still covers them.
Reviewed against USCIS, Department of State and IRS guidance on September 19, 2026. This article provides general information and is not individualized legal or tax advice.